Last updated: August 12, 2026
Quick Answer: For the emergency fund vs savings account decision, stash emergency cash in a savings account if you need quick access, but keep the purpose distinct; for most people, 1 dedicated emergency bucket is enough, while 1 or 2 extra savings buckets handle planned goals. I write about personal finance, and this article on emergency fund vs savings account: what to keep separate and why is here to help you separate “money for shocks” from “money for goals” so you don’t spend the wrong pile at the wrong time. This is information, not financial advice; for your own situation, a qualified adviser can help.
Key Facts
- An emergency fund is a purpose; a savings account is a container.
- 1 dedicated emergency bucket helps reduce accidental spending.
- 2 common jobs for savings are planned expenses and medium-term goals.
- If you are unsure about account rules, check your national regulator or deposit insurer.
- In the U.S., the FDIC and CFPB explain deposit insurance and consumer account basics.
The Real Difference Between an Emergency Fund and a Savings Account
The difference is not the account type. It is the job of the money.
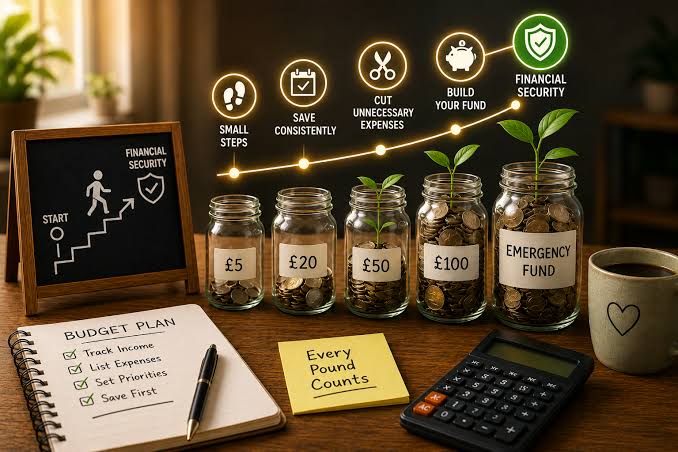
An emergency fund is a purpose. A savings account is a container. You can keep an emergency fund in a savings account, but the account itself does not make the money an emergency fund. What does? Your rule for using it: true emergencies only.
That line gets blurred fast. And once it blurs, mistakes follow. If your “savings” is really 3 goals in one pot — car repair, vacation, and backup cash — you will either overspend it or cling to it too tightly. Ugly either way.
I would separate money like this:
- Emergency fund: job loss, medical gap, urgent home or car repair, travel you cannot avoid for a family crisis, or another real disruption.
- General savings: planned spending, short-term goals, or cash you may want to use soon but do not need immediately.
Say you are setting aside $1,200 for a tire replacement next month. That is not emergency money. A $2,000 job-loss buffer is. A generic article often stops there, which is a bit like handing you a map with half the roads missing. The practical snag is this: the bank may call both accounts “savings,” but your habits should not.
Honestly, I prefer a setup where the emergency fund sits in its own account, named clearly if the bank allows it, so the label reminds you not to raid it for non-emergencies.
The danger of mixing everything together is behavioral, not technical. If the balance looks large, it starts feeling spendable. If it looks tiny because it is split badly, you may not have enough for a real emergency when one shows up. The answer is not clever investing. It is cleaner buckets.
For a plain definition of savings products and deposit protection rules, I’d point you to your country’s consumer finance authority or deposit insurer; in the U.S., the FDIC and CFPB both publish straightforward explanations of how bank accounts work and what deposit insurance does and does not cover. In practice, the product matters less than the rules attached to it.
Emergency Fund: Who Should Actually Use This (and Who Shouldn’t)
For anyone with unstable income, hard-to-cut expenses, or very little wiggle room, an emergency fund is the better fit. That includes freelancers, commission-based workers, single-income households, caregivers, and anyone for whom a surprise bill would cause real stress.
Speed is the whole point here. You want cash that is easy to reach when life goes sideways. That is why people commonly keep it in a savings account rather than in an investment account or locked product. Easy access matters more than maximizing return. And yes, I’m being careful with that wording on purpose: an emergency fund is not there to chase growth. It is there to be ready.
Its weakness is plain: easy access also makes misuse easier. If the cash is sitting next to your checking account and your discipline is shaky, it may not stay reserved for emergencies. Then the cushion turns into a sponge — dinner here, a subscription there, a sale you did not need. Poof.
So who should skip the classic emergency-fund setup? Someone with no income and no near-term cash flow should not confuse “I opened a savings account” with “I’m protected.” If money coming in is too low to rebuild a reserve, the first job is stabilizing income and expenses, not fine-tuning account labels. Also, if you have high-interest debt and no buffer at all, your plan may need a different order of operations than a simple “save first” rule. That is exactly where personal advice matters.
Keep the reserve separate from spending money, but not separate from access. Make it hard to use and you may stall during a genuine emergency. Make it too easy to tap and you defeat the point. That tension is the whole game.
Savings Account: The Specific Situations Where It Wins
A savings account wins when the money has a job, just not a crisis job. That makes it the right place for planned expenses and medium-term goals because you get a clean boundary without locking the cash away.
This is where a generic article often gets lazy and says, “Just put your money in savings.” Thin advice. I would split savings into categories:
- short-term goals, like a repair, move, or travel expense
- irregular bills, like annual insurance or school costs
- a buffer for a known upcoming expense
- the emergency fund itself
The upside of a separate savings account is mental clarity. You can watch progress on a goal without mentally mixing it with emergency money. That lowers the temptation to borrow from one pile for another. If your vacation fund sits beside your emergency reserve, every balance check turns into mental bookkeeping.
The trade-off is friction. Too many accounts can create confusion. If modest balances are spread across 5 subaccounts, you may not know what is available for what. In practice, a reader with simple finances often does better with fewer buckets, not more.
A savings account also wins when you need liquidity. Bank savings accounts are generally designed for access, though country-specific rules on transfers and withdrawal limits vary and can change. That makes them suitable for money you may need soon, even if the exact date is unknown.
So I would not use a savings account as a parking spot for money you genuinely do not plan to touch for a long time if your goal is growth rather than access. But that is a different decision from the emergency-fund question. For this article, the point is simple: savings accounts are for holding money; emergency funds are for surviving a disruption. Sometimes they overlap. They are not the same job.
For broader account basics, the U.K.’s MoneyHelper and the U.S. CFPB both have reliable consumer guides; if you are elsewhere, your national financial regulator is the right place to check local rules.
The Honest Side-by-Side
The cleanest way to decide is to compare what changes your life when the money is needed.
| Criteria | Emergency Fund | Savings Account | Winner for this condition |
|---|---|---|---|
| Purpose | Unexpected disruption | General holding bucket for money | Emergency fund, if the goal is crisis protection |
| Access | Should be quick | Usually quick, depending on the bank | Tie for access; the account type alone does not decide it |
| Behavioral clarity | Clear “do not spend lightly” rule | Easy to blur with other cash | Emergency fund |
| Best use of the balance | Unexpected necessity | Planned or flexible savings goals | Depends on the job of the money |
| Risk of misuse | Lower when separate and labeled | Higher if it doubles as spending money | Emergency fund |
| Emotional benefit | Creates peace of mind during a shock | Creates progress toward a goal | Tie; they solve different problems |
| Account count | One dedicated bucket is often enough | Can support multiple goals | Savings account, if you need sub-buckets |
| Worst-case downside | May be too easy to tap if not disciplined | May hide the absence of real emergency protection | Emergency fund, if discipline is the issue |
| Fit for short-term goal money | Poor fit | Good fit | Savings account |
The row people overlook is the last one: a savings account can hold an emergency fund, but not every savings balance should be treated like emergency money. If you do that, you risk raiding the cushion for convenience. That math stops working fast.
This comparison has one weakness. It can make the choice sound more technical than it really is. It is not. Ask yourself this: will the money be needed because life broke, or because you planned to use it? If the answer is “planned,” it belongs outside the emergency bucket.
Our Verdict: Which One to Choose and Why
Choose an emergency fund if your main need is protection from surprise expenses or income loss. Pick a separate savings account bucket if your main need is to organize money for a planned goal. Neither works well if the money is so tight that setting aside cash would leave you unable to cover essentials; in that case, your first move may need to be a budget reset or professional advice.
My recommendation is direct: keep the emergency fund separate in your mind, and usually separate in its own savings account too. That gives you clarity and lowers the odds of accidental spending. If your bank allows nicknames or multiple subaccounts, I would use them. If it does not, a plain savings account with a strong mental rule still works.
Here is the practical difference I want you to keep: an emergency fund is not “extra savings.” It is the money that stops one bad week from becoming a long recovery. A regular savings account can hold that money, but it can also hold money for a new phone, holiday, or repair. Those are not the same thing, and pretending they are causes trouble.
A generic article would say “save for emergencies.” True, but thin. What matters is where the money sits and what rule you attach to it. If the rule is fuzzy, the money will be fuzzy too. If the rule is crisp, the account can do its job.
When to Reconsider This Choice Entirely
There are a few cases where the usual recommendation flips or needs a second look.
First, if your emergency fund keeps getting drained for non-emergencies, the issue is not the account. It is the structure. You may need a separate account at a different bank, a stricter naming system, or a better budget boundary.
Second, if you have very irregular income, a single emergency fund may need to do double duty as income smoothing. In that case, part of the balance is still emergency money, but part is a cash-flow buffer. The label matters less than your withdrawal rules.
Third, if your country offers different deposit rules, tax treatment, or account features, the best storage place can change. I cannot give one universal rule because finance laws are local and they change. Check local guidance before making assumptions.
Fourth, if you are carrying expensive debt and have no cash cushion, the usual “build emergency savings first” advice may not fit your situation cleanly. The right sequence depends on interest costs, income stability, and the size of the cushion you can realistically maintain. That is where a qualified adviser can be worth the conversation.
The common thread is simple: the account type is the easy part. The harder part is deciding what role each dollar plays.
FAQ
Is an emergency fund just a savings account?
No. An emergency fund is a purpose, not a product. A savings account is one possible place to keep it.
Should I keep my emergency fund and savings in separate accounts?
Usually yes, if separation helps you avoid spending the wrong money. If too many accounts confuse you, one account with clear labels can still work.
Can I use a savings account for both emergencies and goals?
You can, but I do not think it is ideal. Mixing purposes raises the odds that emergency money gets spent on planned purchases.
What counts as a real emergency?
A true emergency is an unexpected expense or income problem that needs attention now, not something you simply want sooner than planned.
Where should I check account rules for my country?
Start with your national financial regulator, consumer finance authority, or deposit insurer. Rules on access, protection, and transfers are not the same everywhere.